Summary of Living with My Teacher! Manhwa
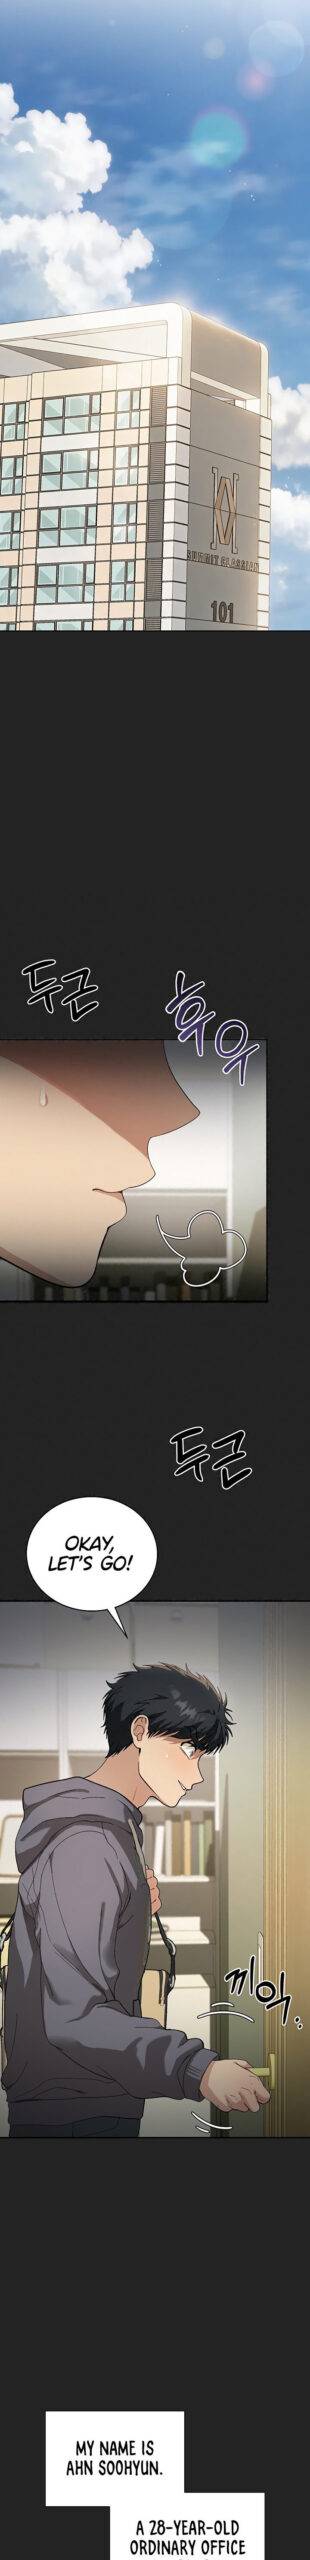
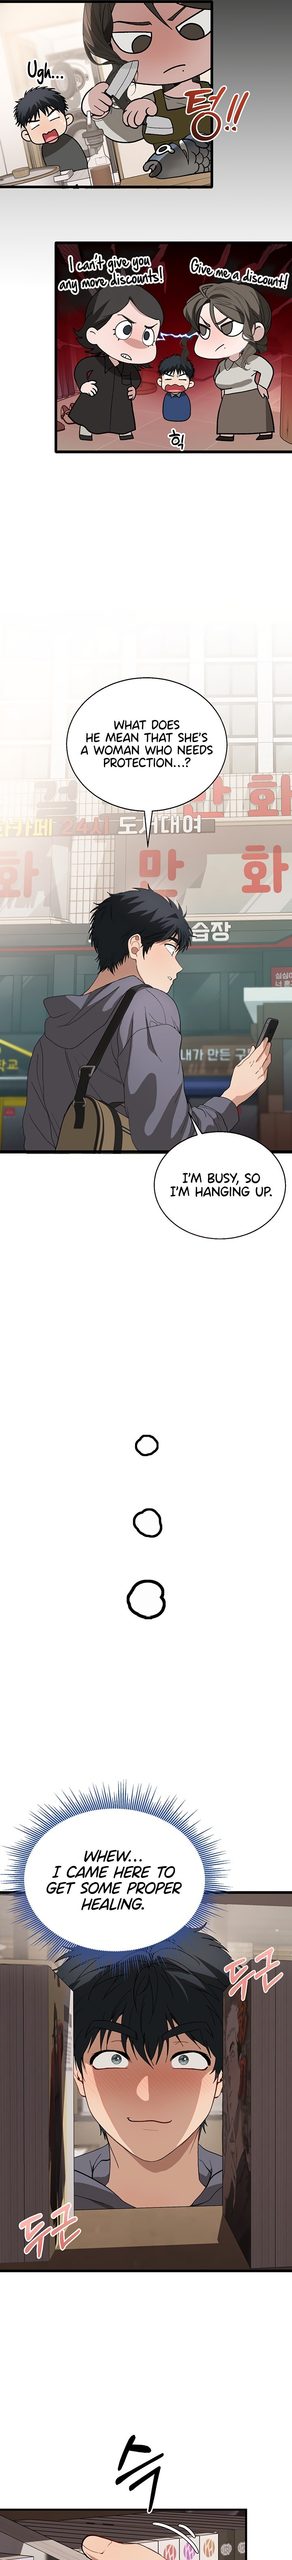
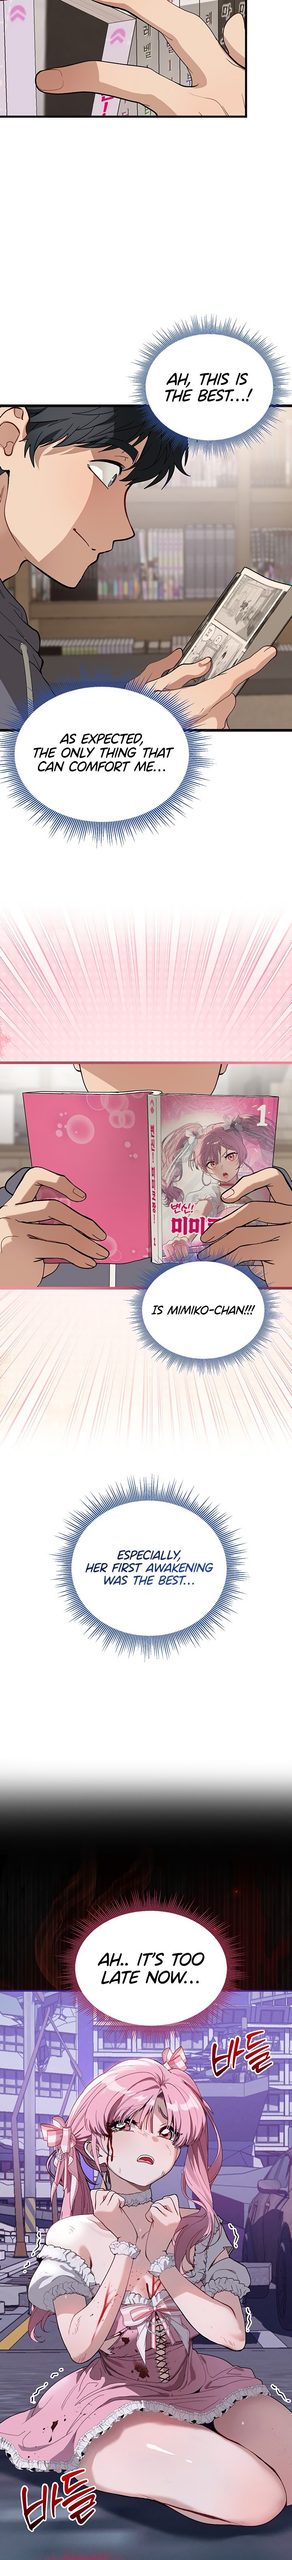
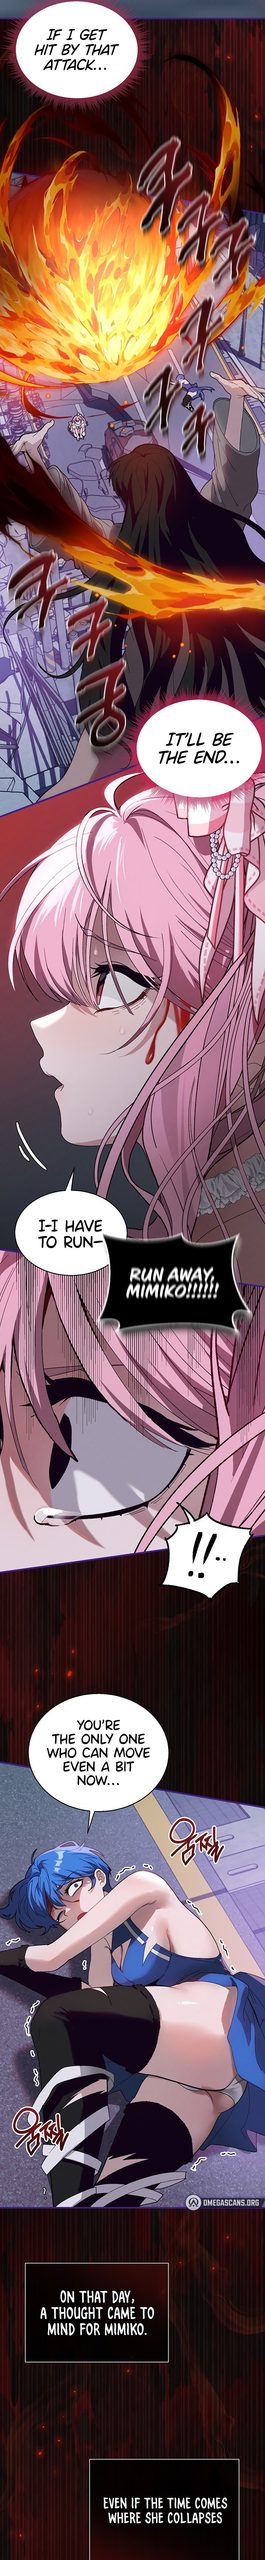
Soohyun loses his place to live after falling victim to a rental deposit scam. Of all people, he ends up staying at his former homeroom teacher’s house. The woman he once found intimidating has a secret(?) side to her…? “You can keep this secret from the others, right…? In return, I’ll help you relax ♥️ ”
Living with My Teacher! Manhwa also known as 선생님과 산다. This on-going webtoon was released in 2026. This series was written by Seokji and illustrations by Seokji. Living with My Teacher! Webtoon is about Drama, School Life story.





















Chapter 2: https://thedailyfeed.online/2026/09/21/living-with-my-teacher-chapter-2/
Mortgage Refinancing in 2026: When It Makes Sense and How to Do It Right
Refinancing a mortgage can lower your monthly payment, shorten your loan term, or free up cash for other goals — but it isn’t automatically a good move for every homeowner. Closing costs, break-even timelines, and current rate conditions all factor into whether refinancing actually saves you money. This guide walks through how refinancing works, when it’s worth considering, and how to avoid the most common mistakes.
What Is Mortgage Refinancing?
Refinancing replaces your existing mortgage with a new loan, ideally with better terms — a lower interest rate, a different loan length, or a shift from an adjustable rate to a fixed one. The new loan pays off the old one, and you begin making payments under the new terms. Homeowners refinance for several reasons: to reduce their interest rate, to tap into home equity, to remove private mortgage insurance, or to change their loan structure entirely.
Common Types of Refinancing
Rate-and-Term Refinance
This is the most common type. You replace your current mortgage with a new one at a different interest rate, a different term, or both — without changing the loan balance significantly. It’s typically used to lower monthly payments or pay off the home faster.
Cash-Out Refinance
This lets you borrow more than you currently owe and take the difference in cash, using your home equity as collateral. It’s often used for home renovations, debt consolidation, or major expenses, but it does increase your loan balance and monthly payment.
Cash-In Refinance
Less common, this involves paying down a portion of your principal at closing to qualify for better terms or to eliminate mortgage insurance.
Streamline Refinance
Available for certain government-backed loans (FHA, VA, USDA), streamline refinancing simplifies the process with reduced documentation and, in some cases, no appraisal requirement.
When Refinancing Makes Sense
- Interest rates have dropped meaningfully since you took out your loan — generally a full percentage point or more, though even smaller drops can be worthwhile on larger loan balances.
- Your credit score has improved significantly, qualifying you for a better rate than when you originally borrowed.
- You want to eliminate private mortgage insurance (PMI) after building enough equity.
- You want to switch from an adjustable-rate to a fixed-rate mortgage for payment stability.
- You plan to stay in the home long enough to recoup closing costs — this is the most important factor and is often overlooked.
Calculating Your Break-Even Point
Refinancing isn’t free. Closing costs typically run 2–5% of the loan amount, covering appraisal fees, origination fees, title insurance, and other charges. To determine whether refinancing is worthwhile, calculate your break-even point:
Break-even (months) = Total closing costs ÷ Monthly savings
For example, if refinancing costs $6,000 and saves you $200 per month, your break-even point is 30 months. If you plan to stay in the home longer than that, refinancing likely makes financial sense. If you might sell or move before then, the savings may not outweigh the upfront cost.
Steps to Refinance Your Mortgage
- Check your credit score and credit report. Errors or a low score can significantly affect the rate you’re offered.
- Determine your home equity. Most lenders require at least 20% equity for the best rates, though options exist for less.
- Shop multiple lenders. Rates and fees vary considerably; getting at least three quotes is standard advice from financial regulators.
- Compare the full cost, not just the rate. A slightly lower rate with high fees can cost more than a higher rate with low fees.
- Lock your rate once you find a favorable offer. Rates can fluctuate daily, and a rate lock protects you during underwriting.
- Prepare documentation. Expect to provide pay stubs, tax returns, bank statements, and details about your current mortgage.
- Close on the new loan. Review the closing disclosure carefully before signing, and confirm all terms match what you agreed to.
Common Mistakes to Avoid
- Refinancing without calculating the break-even point. A lower rate doesn’t always mean savings if you move before recouping closing costs.
- Only comparing interest rates. Origination fees, points, and closing costs can vary significantly between lenders offering similar rates.
- Extending the loan term unnecessarily. Resetting to a new 30-year term can lower monthly payments but increase total interest paid over the life of the loan.
- Ignoring the impact on your credit score. Rate shopping within a short window (typically 14–45 days depending on the scoring model) usually counts as a single inquiry, but applying over a longer period can ding your score multiple times.
- Not reading the fine print on adjustable-rate refinances. Understand how and when the rate can change after any introductory period ends.
Final Thoughts
Mortgage refinancing can be a powerful financial tool when the timing and terms align with your goals, but it requires careful math rather than assumptions. Before committing, run the numbers on your specific break-even point, compare offers from multiple lenders, and consider how long you realistically plan to stay in your home. Speaking with a mortgage advisor or financial planner can also help clarify whether refinancing fits into your broader financial picture.
